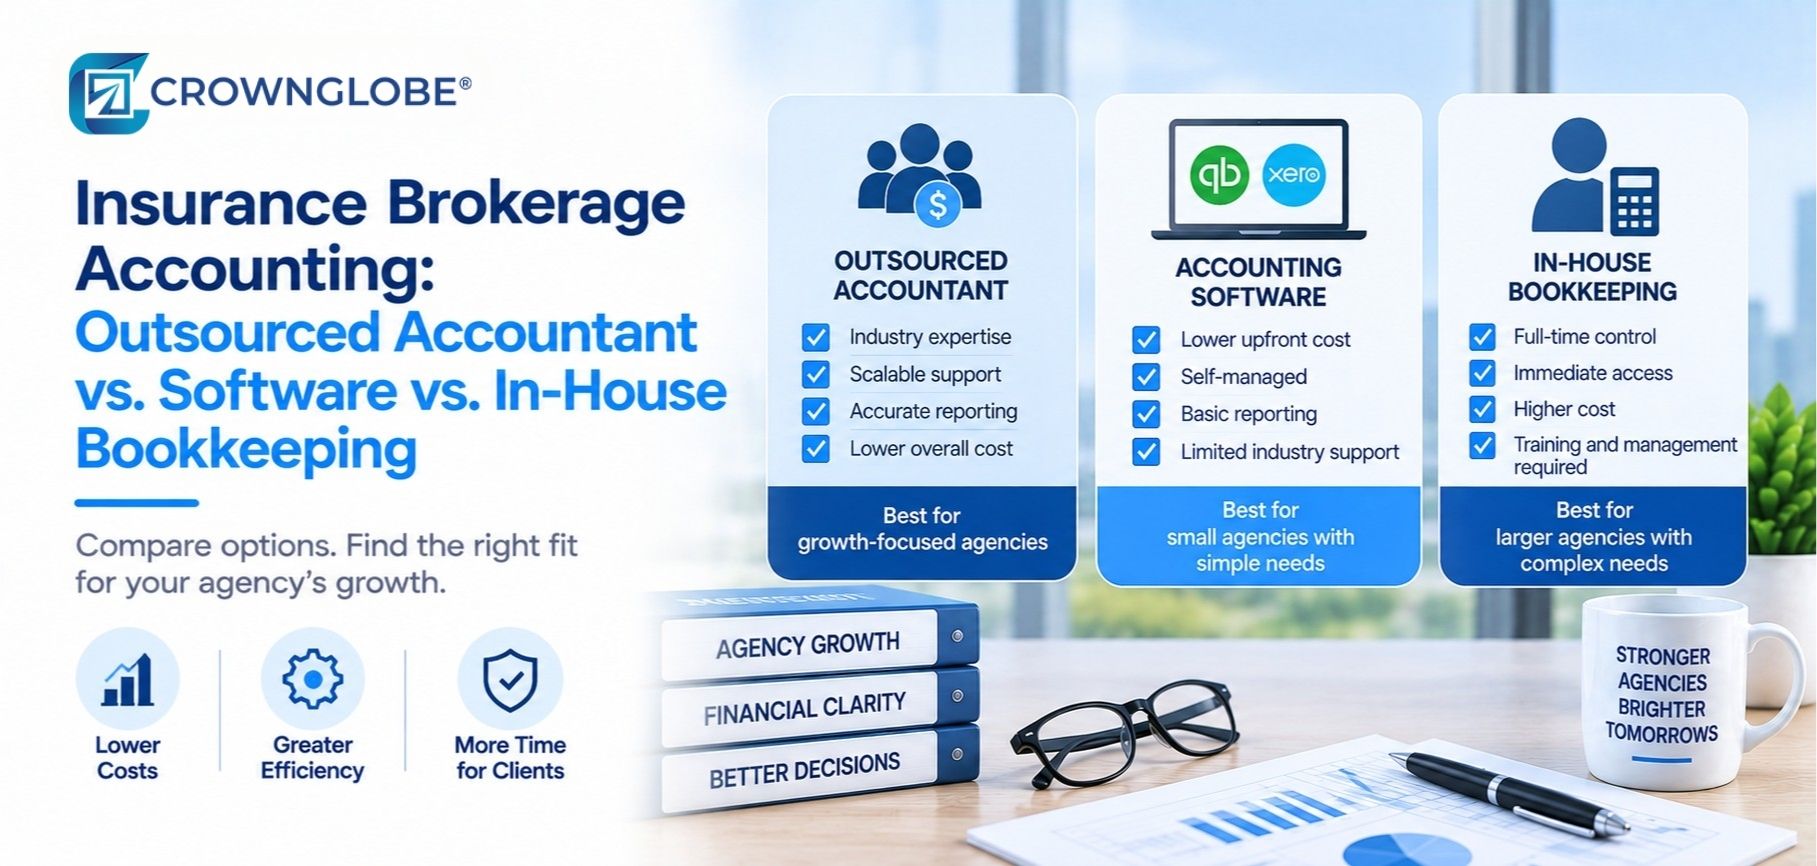
Verdict: Which Accounting Model Fits Your Brokerage?
Choose in house whenyour brokerage has enough capable accounting capacity to handle daily bookkeeping, insurance specific exceptions, reconciliations, review, and continuity without relying on one person's undocumented knowledge.
Choose software led bookkeeping whena competent internal accounting owner is already in place and the main constraint is manual processing, reconciliation, or reporting. Accounting software for insurance brokers can support the workflow, but it does not become the party responsible for the books.
Choose outsourced insurance accounting whenthe brokerage needs dependable recurring bookkeeping, reconciliation, close, or reporting capacity and can clearly separate provider work from internal approvals, judgment, and management oversight.
Choose a hybrid whenbrokerage specific judgment and approvals should stay internal while an outside team handles repeatable accounting execution under documented rules.
01 · The Models
Outsourced Accountant vs. Software vs. In House: The Three Models, Scored
Insurance brokerage accounting combines ordinary bookkeeping with workflows that require insurance context: carrier commission statements, producer activity, direct bill and agency bill transactions, chargebacks, reconciliation differences, and handoffs between the agency management system and the general ledger. The right model is the one that gives those workflows a clear owner and a dependable review path. The scorecard below uses CrownGlobe editorial fit signals, not objective product ratings. More dots indicate that a model tends to provide more of a given capability by design; they do not mean it will always outperform the alternatives.| Decision dimension | In house | Software led | Outsourced insurance accountant |
|---|---|---|---|
| Brokerage specific context available day to day | ●●● | ●●● | ●●● |
| Accounting judgment built into the model | ●●● | ●●● | ●●● |
| Lower dependence on owner/manager processing time | ●●● | ●●● | ●●● |
| Continuity beyond one individual | ●●● | ●●● | ●●● |
| Flexible recurring capacity | ●●● | ●●● | ●●● |
| Process documentation discipline | ●●● | ●●● | ●●● |
| Independent review layer | ●●● | ●●● | ●●● |
| Direct internal control over priorities | ●●● | ●●● | ●●● |
| Technology ownership stays inside | ●●● | ●●● | ●●● |
| Close accountability can be clearly assigned | ●●● | ●●● | ●●● |
How to read the scorecard
The scorecard is most useful when you compare it with the weakness in your current model. A brokerage that already has a strong internal accountant may benefit more from better software and process documentation than from changing who performs the work. A brokerage with modern software but no dependable close owner has a different problem: another application will not fix a gap in accountable accounting capacity. Continuity deserves particular attention. An in house model can be resilient when work is documented and more than one person can cover critical tasks, yet it can become fragile when one employee holds most of the process knowledge. The same principle applies to outsourcing: evaluate a provider on documented procedures, review coverage, and handoffs rather than assuming continuity simply because the provider has a larger team. The dots describe the operating model's typical fit, not the quality of a particular employee, provider, or software implementation. A well run version of any model can outperform a poorly designed alternative. The point is to make visible which responsibilities your brokerage still needs someone to own.In house accounting
An in house bookkeeper or accountant can stay close to day to day brokerage operations, answer internal questions quickly, and build detailed knowledge of producers, carriers, workflows, and management preferences. In return, the brokerage also owns recruiting, training, review, backup coverage, process documentation, and continuity. The in house model can fit well when the accounting workload justifies dedicated capacity and management can provide a genuine review layer instead of relying on one person to prepare and approve everything.Software led bookkeeping
Software led bookkeeping keeps accounting responsibility inside the brokerage while using QuickBooks, Xero, automation, bank feeds, reconciliation tools, or related systems to reduce manual work. It fits best when someone internally can decide how transactions should be classified, resolve exceptions, review reconciliations, and own the close. Software can organize and automate parts of the process. It cannot decide who is accountable when a carrier statement does not tie, a producer transaction is unusual, or the books require a judgment call.Outsourced insurance accounting
Insurance accounting services can move clearly defined recurring work to an outside team. CrownGlobe's documented outsourced accounting for recurring bookkeeping and close support includes bookkeeping, reconciliations, AP/AR, close, and financial reporting support. The outsourced model works best when scope, approvals, review, access, and exception ownership are explicit from the start. An insurance accountant or outsourced accounting team should never become an invisible black box between the brokerage and its books. For a narrower two way decision focused on operating QuickBooks internally versus outsourcing the bookkeeping process, see QuickBooks versus outsourced bookkeeping for insurance agencies.02 · Hybrid
Where a Hybrid Model Can Fit an Insurance Brokerage
A hybrid model separates accounting ownership from accounting execution. It can fit when brokerage leadership wants to keep approvals, judgment, and management context internal while assigning repeatable finance work to an outside team.Keep inside the brokerage
- Accounting policy and unusual item judgment
- Payment and banking approvals
- Final management decisions
- Ownership of source information and key exceptions
- Provider oversight and access decisions
- Final review or sign off where appropriate
Deliver externally where scoped
- Recurring bookkeeping
- Routine reconciliations
- AP/AR support where included
- Month end close preparation and recurring close work
- Standard financial report preparation
- Documented recurring exception follow up
03 · Diligence
What to Verify Before Choosing an Accounting Model
The delivery model may change, but the diligence questions should remain largely the same. Software, employees, and outside providers all need a clear operating framework.- Named accounting owner. Who is ultimately responsible for the books and the close?
- Insurance workflow capability. Who understands commissions, carrier statements, producer activity, chargebacks, and unusual exceptions?
- Review layer. Who checks reconciliations, classifications, recurring adjustments, and unresolved differences?
- Continuity. What happens when the primary person is unavailable?
- System handoffs. How do the agency management system, accounting platform, bank activity, and supporting records fit together?
- Access control. Who receives system access, who approves it, and how is it removed when responsibilities change?
- Close calendar. What information is due, from whom, and by when?
- Data ownership. Who controls exports, historical records, workpapers, and process documentation?
- Exit path. If the brokerage changes people, providers, or software, how will open items and records transfer?
04 · Transition
What It Takes to Change Accounting Models
Changing accounting models is more than a staffing or software decision. The transition has to preserve the books, open items, system access, and review process while responsibilities move from one owner to another.
1
Discovery
Document the current chart of accounts, recurring workflows, systems, user access, close calendar, open reconciliation items, recurring adjustments, and known exceptions. That inventory defines what the new model actually needs to take over.
2
Cleanup and Design
Resolve material cleanup issues before they are carried into the new process. Then define the target operating model, reporting calendar, systems of record, and the work that should remain internal.
3
Responsibility Map
Document who prepares, reviews, approves, and resolves exceptions. Moving the tasks is only part of the transition; ownership also has to be clear.
4
Parallel Close
Where practical, run the old and new process through a controlled close or equivalent operating cycle. The goal is to surface missing inputs, unclear approvals, access gaps, and reconciliation differences before the prior process is retired.
5
Handover and Stabilize
Complete access changes, transfer process documentation, assign ownership of open items, and review the new operating model after it has run under normal conditions. Any adjustments should be documented instead of being absorbed informally into one person's routine.The most useful question is often not “Which software should we buy?” or “Should we outsource?” It is “Who owns this accounting decision?” Once ownership is clear, software and staffing choices become much easier to evaluate.
Questions
Questions Insurance Brokerage Owners Ask
It can be enough when the brokerage already has a capable internal owner for bookkeeping decisions, reconciliations, exceptions, review, and close. QuickBooks and Xero can support transaction processing, reconciliation, reporting, and collaboration, but the software does not take responsibility for the correctness of the books or resolve every brokerage specific judgment call.
An in house model can fit when the brokerage has enough recurring work to justify dedicated capacity, wants accounting knowledge embedded in daily operations, and can provide appropriate review and backup coverage. There is no universal revenue, headcount, or transaction threshold that determines the answer.
Outsourcing is worth evaluating when recurring bookkeeping, reconciliation, close, or reporting work needs more capacity or specialist support than the brokerage wants to maintain internally. The scope should still identify what the provider prepares, what the brokerage approves, who reviews exceptions, and who owns final financial decisions.
An insurance accountant can interpret transactions, investigate exceptions, apply accounting judgment, review reconciliations, explain financial results, and take responsibility for defined parts of the close. Software can support those activities, but it does not replace the person or team accountable for them.
Yes. A brokerage can keep approvals, judgment, management decisions, and provider oversight internally while assigning recurring bookkeeping, reconciliations, close preparation, or reporting support externally. The key is to document the responsibility split rather than assuming everyone understands it.
Start by documenting the current process and open issues. Clean up material problems, define the new responsibility map, test the new workflow through a controlled operating cycle where practical, transfer access and documentation carefully, and assign ownership for any unresolved items before the old process is retired.
Sources & Further Reading
- IRS Recordkeeping: irs.gov
- IRS Use of Electronic Accounting Software Records: Frequently Asked Questions and Answers: irs.gov
- Intuit QuickBooks Bank Reconciliation: quickbooks.intuit.com
- Xero Accounting Software for Insurance Companies: xero.com
- CrownGlobe Insurance Agency Bookkeeping and Accounting: crownglobe.com
- CrownGlobe Outsourced Accounting: crownglobe.com
General Information Disclaimer
CrownGlobe provides outsourced accounting services, so this comparison is not disinterested. The scorecard reflects editorial fit judgments rather than independent performance measurements and should be applied to CrownGlobe as well as other options. This article provides general information only and is not legal, tax, accounting, regulatory, employment, or software advice. Requirements and appropriate accounting processes can vary by brokerage, jurisdiction, contract, systems, and facts. Obtain appropriate professional advice for material accounting, tax, legal, regulatory, employment, or contractual decisions.